

Dear reader,
Two stories shaped the week, one made in America and one made rather closer to home, and for once they were pulling in the same direction.
The American story was Nvidia, who else. The chip giant reported quarterly revenue of $96.2bn, up 106% on a year ago, and then had the cheek to guide for around 70% growth next year, well clear of the 44% Wall Street had pencilled in [1]. The shares jumped, the Nasdaq followed, and half the world’s technology stocks were dragged along for the ride. Washington gave the market plenty else to chew on. The week brought a fresh escalation in the trade war with Canada, a threatened 50% tariff on cars, trucks and steel from the new year, with Ottawa promising to match it dollar for dollar from 8 September, and a new round of sanctions on Iran, the Treasury’s Scott Bessent vowing an “economic D-Day” on Tehran. Under all that noise, American inflation still refuses to behave, its core measure stuck at 3.3%, which set up the week’s real event. New Fed chair Kevin Warsh, who replaced Jerome Powell in the spring, used his first Jackson Hole speech on Friday to plant his flag on inflation, calling it still too high and warning that the next move on rates could be up as easily as down. Anyone hoping for a cut left disappointed. For readers over here it hardly matters. There is so little technology in the FTSE that Nvidia's blowout barely registered in London, the same quirk that left the index looking like a wallflower right through the AI boom. It is built on oil, banks and miners, not chips.
Closer to home, the story was oil, and oil blinked. Word got round that Iran and Oman are talking about reopening the Strait of Hormuz, the tanker chokepoint whose closure had kept Brent jammed near $93 all month, and crude slipped on the hint [2]. It sounds like a footnote, but it is the pressure valve I was banging on about last week. A softer oil price feeds into softer inflation, which eases the pressure on gilt yields and hands the Bank of England a little more breathing room, and cheaper money is oxygen for anything in this market that lives on borrowed cash. Then Westminster added a shove of its own, dishing out the first slice of a £39bn affordable homes programme to the builders and handing Vistry its best day in months [3]. Cheaper oil and a government cheque in the same week, both aimed squarely at the parts of the market everyone had written off.

Last week’s losers, this week’s winners
This is the same rates story as last week, just read from the other end. A week ago two things were running at once. Money was piling into hard assets and lifting the miners, while at home a climbing oil price was dragging gilt yields higher and squeezing anything that lives on the cost of borrowing. Take the heat out of the oil, which is what this week did, and half of that machine runs backwards.
The miner show it cleanest. Last week five of them jammed into the top of the FTSE 100 as gold and silver went vertical. This week the metal came off the boil and they went quiet with it, leaving only Anglo American (LON:AAL) on the riser board, up 4.33%, and even that on copper and the industrial trade rather than the precious-metals leverage that had done all the damage before. Nobody dumped the sector in a hurry. The money just found somewhere better to be.
That somewhere was the wreckage of the last two years. The rate-sensitive domestic names that got left for dead while borrowing costs were rising caught a bid the moment the pressure eased, and the mid-cap board tells the story without much help. A housebuilder out in front, a recruiter and an office landlord a step behind. None of it an accident.
The movers
A scan of the week, with a verdict on each. Signal means a genuine change in the story. Noise means a move to look past.
Risers, FTSE 100
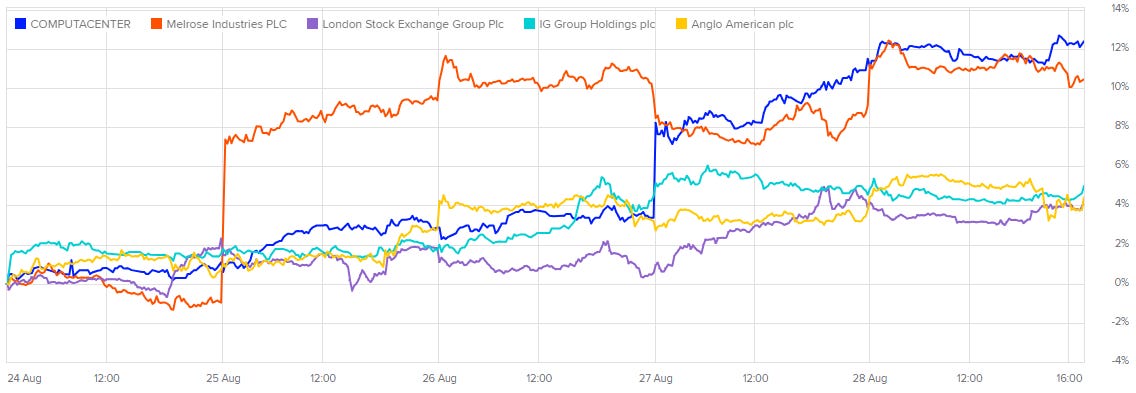
Computacenter (LON:CCC), +11.50% to 5,670.00p, lled the index, and it did it on Nvidia’s coat-tails. The group kits out data centres for the hyperscale cloud giants, the handful of huge customers doing the AI build-out, so when Nvidia’s results this week hammered home how much of that hardware is being bought, Computacenter caught the updraft and touched a fresh record high, helped along by a broker upgrade to buy. It had already raised profit guidance over the summer on strong North American hyperscaler demand [4], and the full half-year figures are due on 8 September. Signal.
Melrose Industries (LON:MRO), +9.55% to 515.20p, was a very different kind of good news. A cloud lifted. US prosecutors closed their investigation into the chemical incident at its GKN Aerospace plant in Garden Grove, California, without bringing charges, the company set out a $100m compensation programme for affected residents and businesses, and it now expects to restart production there next month [5]. None of that is trading news, but a stock trades on the removal of a worry as readily as on the arrival of good figures. Signal, though of the overhang-lifted variety rather than the operational kind.
London Stock Exchange Group (LON:LSEG), +5.36% to 9,000.00p, drifted back through the 9,000 mark without a single headline to point to. After a soft few months, this looks like money quietly returning to a high-quality compounder, the data and index business that is more Refinitiv terminals and FTSE Russell licences than actual share trading these days. A bid rather than a story, but a telling one about where the mood went this week.
IG Group (LON:IGG), +4.57% to 1,395.00p, is the spread-betting and trading platform whose fortunes rise with market activity. A jumpy week of oil and rotation is grist to its mill, and I could find nothing company-specific behind the move. Read it as the machine doing what it does when markets get busy. Noise.
Anglo American, covered above, rounds out the list as the last miner standing. Macro.
Fallers, FTSE 100
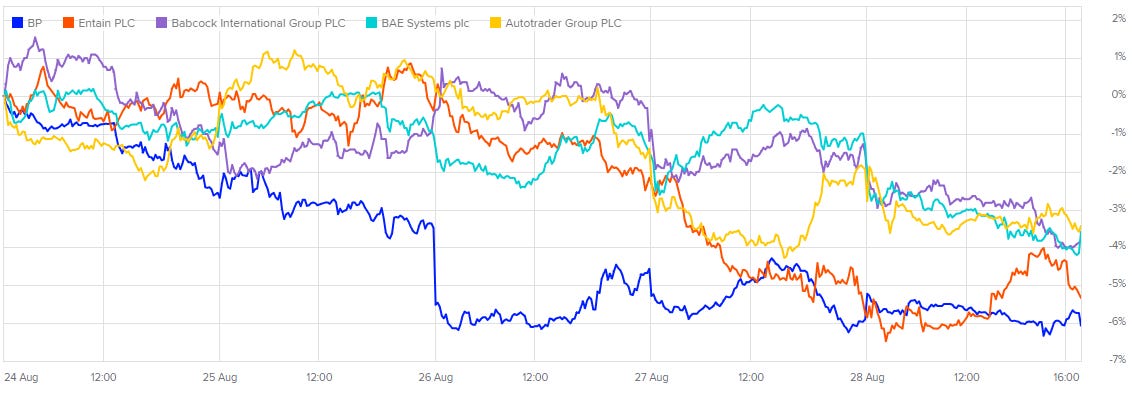
BP (LON:BP.), -6.37% to 514.50p, was the clearest expression of the oil pivot. The same softening crude that set the week’s tone lands hardest on the oil majors, and BP had a second thread running underneath. It is in exclusive talks to sell a package of its Egyptian gas assets to Energean for around $1bn, part of a long effort to shed bits and pay down debt [6]. The share move, though, is mostly the barrel. Signal, on the macro rather than the company.
Entain (LON:ENT), -4.54% to 513.20p, the Ladbrokes and Coral owner, fell without a fresh catalyst I could pin to the week. The sector still has last year’s tax rises weighing on it and a nervous eye on the autumn budget, but nothing new landed. Reads as pre-budget jitters and profit-taking. Noise.
Babcock International (LON:BAB), -4.35% to 1,056.50p, and BAE Systems (LON:BA.), -3.86% to 2,044.00p, were the defence trade taking a breather for the second week running. I said last week that a richly priced sector with nothing fresh to feed it was worth keeping an eye on, and here we are. No bad news at either, just rich multiples, the odd flicker of peace talk in the background, and money rotating elsewhere. Individually noise, but two weeks makes it a pattern, and the pattern is the thing to watch.
Auto Trader (LON:AUTO), -3.44% to 528.00p, is a quality domestic name with no news attached. When the market rotates towards cheap and cyclical, the expensive and dependable get sold to fund it. Noise.
Risers, FTSE 250
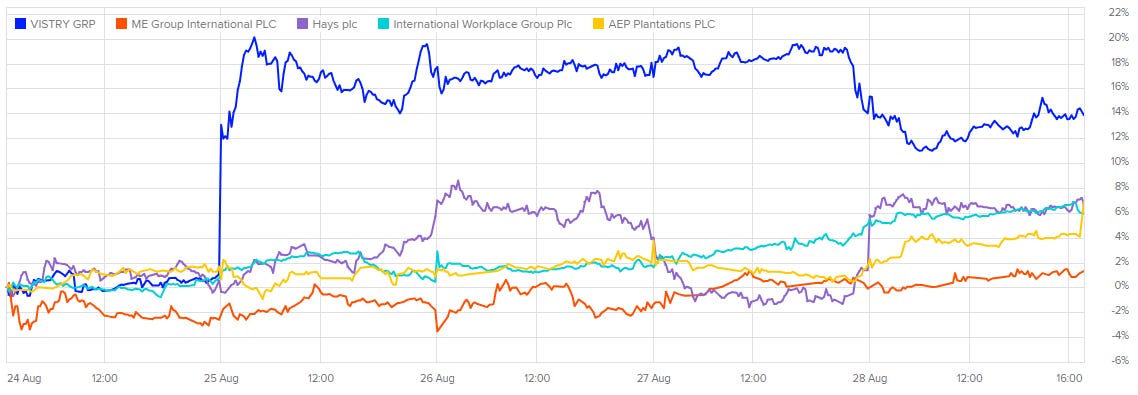
Vistry Group (LON:VTY), +14.45% to 302.60p, had its best day in months. The housebuilder was awarded £350m of direct grant funding under the government’s £39bn Social and Affordable Homes Programme, the largest award available at this stage, enough to build more than 3,000 affordable homes, and was reconfirmed as a strategic partner in the scheme [3]. For a company whose whole model is tilted towards partnership and affordable housing, and whose shares have been battered for two years, this was a rare and large dose of good news. Signal, though with a heavy asterisk I will come back to.
Me Group International (LON:MEGP), +7.27% to 129.80p, the self-service vending business behind the photo booths and the unattended laundrettes, bounced off a share price sitting near its one-year low. I could not find a hard catalyst, so read it as a beaten-down, high-yielding name catching a bid in a week that favoured exactly that. Noise.
Hays (LON:HAS), +7.14% to 77.30p, was the mid-cap turnaround trade I flagged last week, still running. Full-year results confirmed that cost-cutting is offsetting a weak hiring market, and a big broker lifted its price target sharply and pushed the shares to a fresh one-year high [7]. Recruiters are enormously geared to the cycle, so when a business proves its profits are holding up off a low base, the re-rating comes fast. Signal, and the second week in a row the market has paid up for a mid-cap proving its earnings are turning.
IWG (LON:IWG), +6.74% to 190.00p, the flexible office group behind Regus and Spaces, kept grinding higher on a steady buyback and, this week, the same rotation lifting the other domestic cyclicals. No single event, more a rising tide. Part momentum, part rotation.
AEP Plantations (LON:AEP), +6.55% to 205.00p, the palm oil grower with estates in Indonesia and Malaysia, is a small commodity producer riding firm crude palm oil prices, with an ongoing buyback tightening an already thin free float and exaggerating the move. Macro, of the soft-commodity sort.
Fallers, FTSE 250
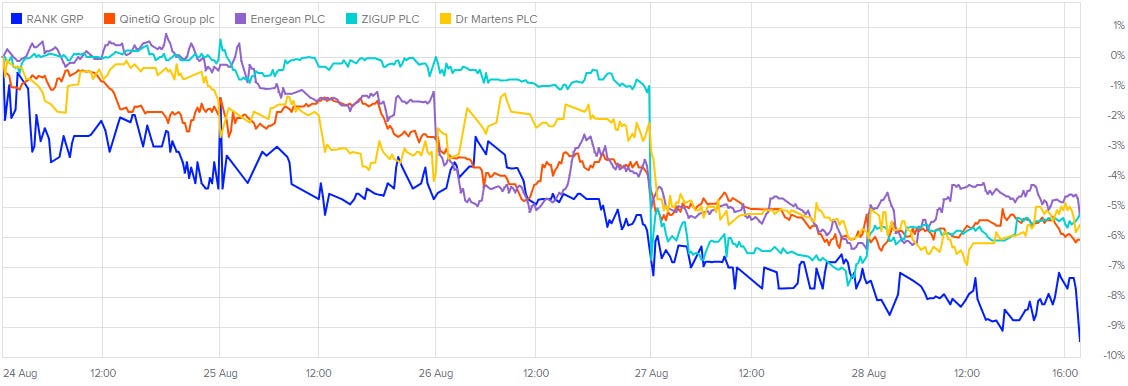
Rank Group (LON:RNK), -7.36% to 103.20p, was the biggest faller on either index, and nothing went wrong at the business. Its full-year results a fortnight ago, which showed profit up a fifth, had popped the shares, and this is largely that pop deflating again. The Grosvenor casino owner is unusually exposed to gambling taxes, so it is the name that flinches first at any budget chatter, and there is plenty of that about. A give-back with a nervous tint rather than a fresh problem. Noise, but the tax sensitivity is real.
QinetiQ (LON:QQ.), -6.02% to 507.50p, was the mid-cap end of the same defence pullback that caught Babcock and BAE. It sits near a one-year high with no bad news attached, the chief executive has been buying shares, and the buyback rolls on, so this is profit-taking, not a wobble. Noise, and part of the defence pattern.
Energean (LON:ENOG), -5.42% to 733.00p, moved on a deal. On 27 August, Reuters reported that it is in exclusive talks to buy BP's Egyptian gas assets, a deal that could raise around $1bn for BP [6], and the shares slid as the news landed, alongside broader weakness in the oil and gas names. The wrinkle is that Energean had itself agreed to offload its own Egypt, Italy and Croatia portfolio to Carlyle back in 2024, only for that to collapse in early 2025 when the buyer could not get it past the Italian and Egyptian regulators. Eighteen months on it is buying into Egypt rather than out of it, and the market tends to look warily on an acquirer. Signal, on the deal.
Zigup (LON:ZIG), -5.26% to 441.50p, the vehicle rental and mobility group, went ex-dividend this week on an 18.2p final payout, meaning new buyers no longer get the next cheque and the price drops by roughly that amount [8]. That accounts for most of the fall. Mechanical.
Dr. Martens (LON:DOCS), -5.13% to 77.60p, also went ex-dividend, though its payout is small, so only part of the drop is mechanical. The rest is the squeezed consumer front of mind again, and a heavily US-exposed bootmaker with a wobbly direct-to-consumer channel is precisely the sort of name that gets sold when shoppers look to be tightening up. Part mechanical, part real.
A note while we are here. Zigup and Dr. Martens going ex-dividend in the same week, on top of Legal & General and Investec doing the same last week, is the late-August dividend calendar quietly nudging a handful of names lower. Worth remembering before reading too much into any single red number this time of year.
Idea of the week: the domestic thaw
Look past the company-specific stories and the shape of the week was a rotation. A housebuilder, a recruiter and an office landlord led the mid-caps, while the miners, the oil majors and the defence names handed money back. That is not a random assortment. It is a bet on the UK domestic economy, made by the parts of the market most punished when oil and gilt yields were rising.
The logic runs straight through the oil price. Cheaper crude means less inflation, which means the Bank of England has more room to cut rates than it did a week ago, which is oxygen for anything sensitive to the cost of borrowing. Housebuilders, recruiters and office operators are about as rate-sensitive as UK equities get, and they have spent two years in the sin bin at valuations that look cheap against their own history. Give the market a reason to believe the pressure is lifting, and the re-rating comes quickly, because so little good news was priced in.
The honest caveat is that this week’s evidence is a bit ragged. Hays moved on its own results, Vistry on a government cheque, and the oil relief itself rests on talks that have barely started. This is a thaw, not a spring. But it is the first week in a while the domestic cyclicals have led, and after two years of being ignored, that is worth filing away.
On the watchlist
Vistry (LON:VTY) sits right on top of the week’s central question, in the same way Fresnillo did last week. It led the mid-caps by a distance, and the thing that lifted it is also the thing to be wary of. The £350m grant is real money, and it lands this year, but it flatters a single year’s delivery. It is a cheque, not a recovery. What the shares have not yet answered is whether private housing demand is actually turning, or whether this is a subsidised sugar rush dressed up as a turning point. The barrel of Brent that eased this week is what buys the Bank of England room to cut and gives the domestic thaw its legs. If the Hormuz talks come to nothing and oil spikes back, the same maths that lifted a housebuilder this week runs in reverse. That is the tension to watch into September.
Thanks for reading,
Ollz
This article is for informational and educational purposes only and does not constitute financial advice. The author may hold positions in securities mentioned. Always do your own research and seek independent financial advice before making any investment decision. Capital is at risk.
Sources
[1] The Motley Fool, https://www.fool.com/coverage/stock-market-today/2026/08/27/stock-market-today-aug-27-nvidia-surges-on-blowout-results-and-surprising-guidance/
[2] ad-hoc-news / Reuters, https://www.ad-hoc-news.de/boerse/news/corporate-news/bp-stock-steadies-as-asset-talks-in-egypt-and-labor-dispute-shape-risk/70009534
[3] Sharecast, https://www.sharecast.com/news/news-and-announcements/vistry-secures-pound350m-in-homes-england-funding-shares-surge--23364182.html
[4] ad-hoc-news, https://www.ad-hoc-news.de/boerse/news/corporate-news/computacenter-stock-jumps-after-guidance-upgrade-on-strong-hyperscaler/69982566
[5] Investing.com, https://uk.investing.com/news/stock-market-news/melrose-shares-jump-8-as-gkn-probe-ends-without-criminal-charges-4845526
[6] Reuters (via OEDigital), https://www.oedigital.com/news/542507-energean-enters-exclusive-talks-for-bp-s-egypt-oil-and-gas-assets
[7] AskTraders, https://www.asktraders.com/analysis/hays-shares-jump-after-recruiter-lifts-profit-guidance-to-top-of-range
[8] DividendMax, https://www.dividendmax.com/united-kingdom/london-stock-exchange/support-services/zigup-plc/dividends
"roughly a $1bn move back into a country it largely exited when it sold its Egyptian and Italian portfolio to Carlyle two years ago [6]."
Energean didn't sell the portfolio. The deal with Carlyle fell through.