

Dear reader,
Back at the desk after a week off (lovely family holiday), and the market did me the courtesy of making the catch-up easy. One theme ran through almost everything that moved. The miners went on a tear, and they did it not because anyone found more metal in the ground but because of what happened to money.
Gold pushed to around $4,512 an ounce mid-week and silver to roughly $67, one of its sharpest sessions of the year. Copper set fresh records on the US Comex exchange, north of $14,300 a tonne. None of that came from the metals themselves. It came from the US Treasury, which said it would at least double the size of its programme for buying back long-dated government debt. That pulled American bond yields lower, and a run of soft US data on jobs and inflation cut the odds the Federal Reserve raises rates again in September from around evens to roughly a third [1]. Lower yields and a weaker dollar make gold and silver, which pay you nothing to hold them, look more attractive by comparison.
The bit worth understanding is why that lands so hard on the shares rather than just the metal. A miner’s costs move slowly while the price it sells at can move fast, so when bullion jumps the extra revenue drops almost straight to the bottom line. That is why the diggers, and the silver names in particular, topped both indices this week while the rest of the market went sideways.
The bigger picture: a tale of two rate stories
Strip the week back and two forces did the work, and they pulled in opposite directions.
The first was the rotation into hard assets I have just described. This is a dollar-and-rates trade, global rather than British, and it plays to exactly the unglamorous, cash-generative, commodity-facing businesses the FTSE 100 is stuffed with. When this trade runs, the tech-light UK index tends to do well for the same reason it looked dull through the whole AI rally. It owns the right things.
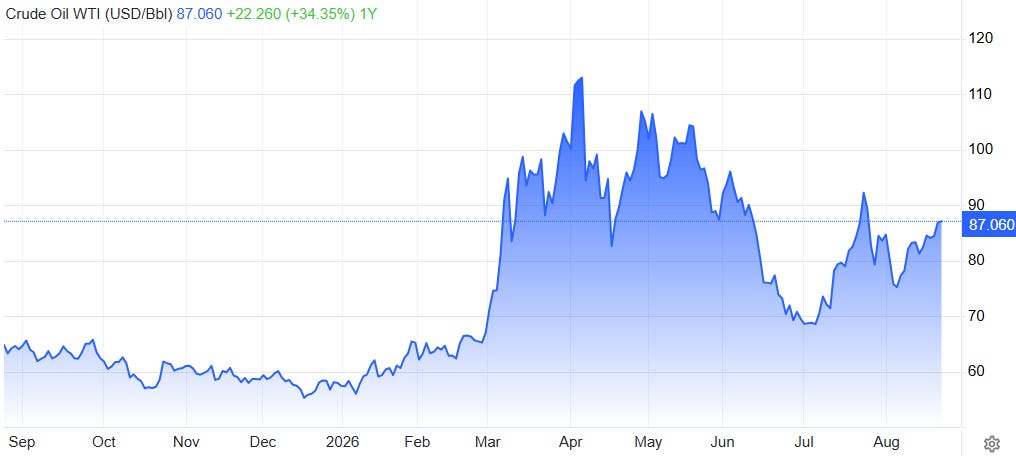
The second force is the one that keeps the champagne on ice. While American borrowing costs were falling, British ones were climbing. UK government borrowing costs, the yield on gilts, hit multi-year highs this week as the supposed 60-day understanding between the US and Iran lapsed with no progress and the Strait of Hormuz still effectively shut, keeping Brent crude near $93 [7]. Higher oil feeds straight into inflation, which is why the gilt market is nervous and why the Bank of England has less room to cut than the Fed. So the same week handed global markets a reason to buy gold and handed the UK domestic economy a reason to worry. That split is why the miners flew while the rate-sensitive and consumer-facing names stayed grounded, and the clearest expression of that second story was a profit warning from one of the high street’s biggest names.
The movers
A scan of the week, with a verdict on each. Signal means a real change in the story. Noise means a move to look past.
Risers, FTSE 100
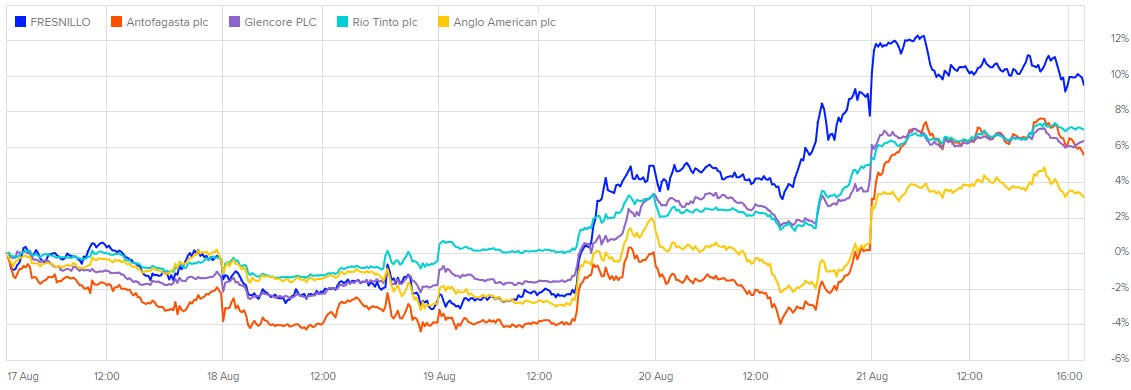
The whole top of the board belonged to one trade. Fresnillo (LON:FRES), +11.77% to 3,219.00p, led the index. It is the purest play on the move, a silver and gold miner whose half-year figures earlier this month showed profit close to tripling on higher prices alone, even as it dug up less metal than a year before [6]. Antofagasta (LON:ANTO), +8.93% to 3,905.00p, Glencore (LON:GLEN), +8.67% to 596.50p, Rio Tinto (LON:RIO), +8.34% to 7,648.00p, and Anglo American (LON:AAL), +5.64% to 4,067.00p, were the copper and diversified names riding the industrial side of the same wave. Macro, all of it. Read the move as a function of the metal price and the rate story behind it, not as five separate company stories.
Fallers, FTSE 100
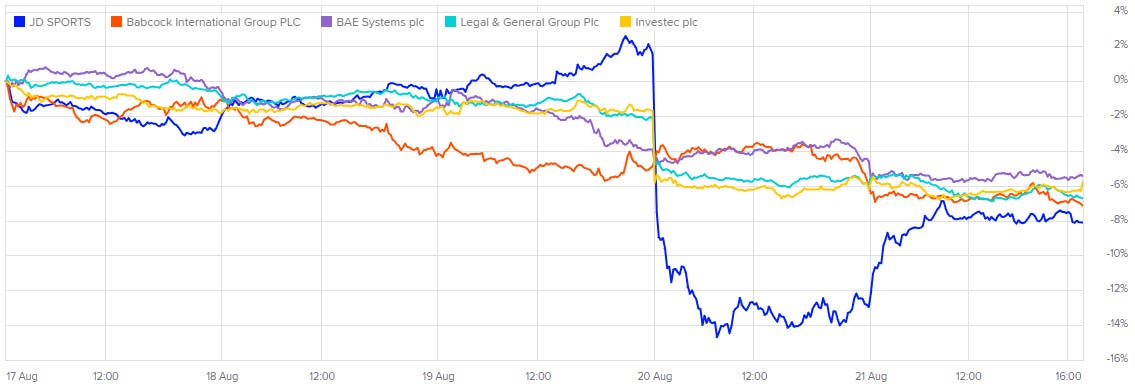
JD Sports Fashion (LON:JD.), -8.46% to 84.60p, was the fall that mattered. The trainer seller cut its full-year guidance for profit before tax and one-off items to a range of £700m to £800m, down from £750m to £850m and below the £852m it made last year [2]. The problem is North America, its single biggest market at roughly a third of sales, where like-for-like takings fell 6.8% in the quarter. Management blamed a jumpy US shopper, a thin release calendar for the big-name trainers that pull people into stores, and a back-to-school season that turned up late. What did the damage was the scale of the reaction against the size of the cut. The company shed around £644m of value on a £50m trim to the middle of its guidance, which tells you the market is bracing for more downgrades rather than pricing a single bad quarter. Signal. The cash position is fine and this is a demand problem, not a balance-sheet one, but the direction of travel is the worry. Full half-year figures land on 23 September
Babcock International (LON:BAB), -7.29% to 1,106.50p, and BAE Systems (LON:BA.), -5.85% to 2,126.00p, were the defence trade taking a breather. Both have had a storming couple of years on rearmament budgets and both now sit on earnings multiples in the high twenties, which leaves no room for disappointment. With money rotating hard into the miners and the odd flicker of Ukraine peace talk in the background, some holders banked profits. No bad news attached to either, so mostly noise, though a richly priced sector with nothing fresh to feed it is worth keeping an eye on.
Legal & General (LON:LGEN), -6.89% to 284.00p, and Investec (LON:INVP), -5.56% to 637.00p, both went ex-dividend on 20 August, meaning new buyers miss the next payout and the price drops by roughly the dividend [8]. But that only goes so far. L&G’s 6.24p is worth about 2% of the price and Investec’s 21p around 3%, so it covers under a third of L&G’s fall and about half of Investec’s. The rest is a genuine decline, money rotating out of the high-yielding financials into the miners rather than a stumble at the companies. Part mechanical, part rotation.
Risers, FTSE 250
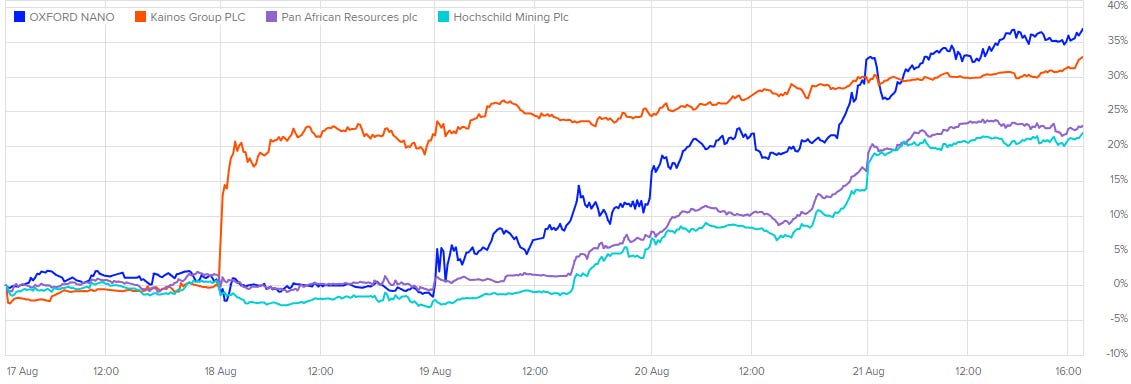
Oxford Nanopore Technologies (LON:ONT), +39.34% to 170.00p, topped the whole mid-cap board, and this one I have looked at before. The full half-year results were the trigger. The revenue figure and its soft growth rate were already known and already a bit disappointing, held back by weakness in China and the Middle East. What the market had not priced was everything below the revenue line. Gross margin, the profit left after the direct cost of making the product, widened by four points to 62.2%, and the closely watched adjusted loss more than halved to £22.1m from £48.3m a year earlier as the company cut its running costs [4]. The new chief executive set out a cleaner strategy focused on the most profitable end-markets, put a revenue ambition of more than $700m by 2030 on the table, and reaffirmed the plan to stop losing money at the operating level in 2027. A fresh licensing deal added a $20m sweetener. The shares had been sitting near a one-year low going in, so a positive surprise on the quality of the earnings had room to run. Signal.
Kainos Group (LON:KNOS), +33.40% to 1,294.00p, was close behind after telling the market its results for the year to March 2027 would come in comfortably ahead of City forecasts [5]. The Belfast IT services group pointed to strong demand for its Workday consulting work and its digital projects, a record order backlog, and momentum carrying over from a year of double-digit revenue growth. It pre-announced a beat, in effect, and the market wasted no time. Signal. Half-year numbers are due on 9 November.
Pan African Resources (LON:PAF), +25.32% to 136.10p, and Hochschild Mining (LON:HOC), +24.83% to 636.00p, were the mid-cap end of the metals move, pure plays on gold and silver with the same leverage that lifted Fresnillo. Macro. When bullion runs this fast, the smaller, higher-cost producers tend to run hardest of all.
Fallers, FTSE 250
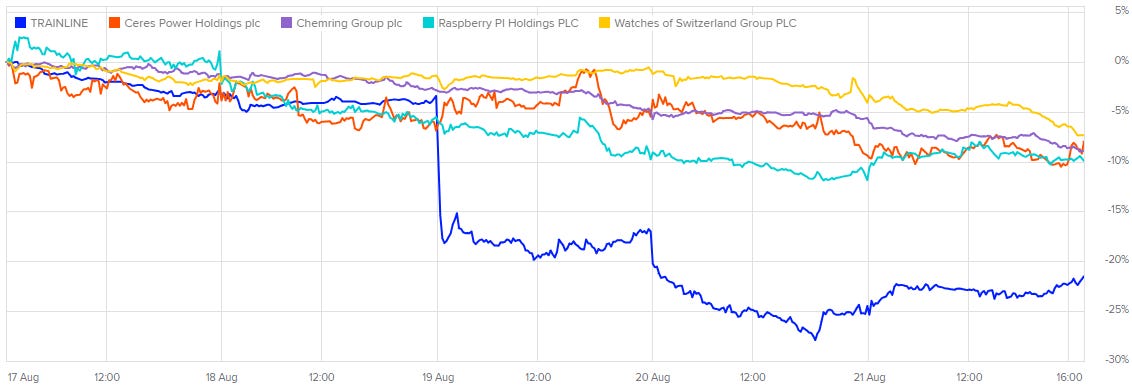
Trainline (LON:TRN), -22.37% to 197.50p, was the biggest faller on either index, and nothing changed in how the business is trading. What changed is that the Competition and Markets Authority, the UK’s competition regulator, opened a formal investigation into how the ticketing app presents its booking fees [3]. The concern is what the regulator calls drip pricing, where compulsory charges appear later in the checkout rather than in the price you first see. The telling part is the maths. The two-day fall wiped out something like four times the largest fine the company could face, which means the market is not fussed about the penalty. It is worried about the model, because if mandatory fees have to be shown in the headline price, that goes at the economics of a division that brings in nearly half of group revenue. This lands on top of the long-running worry about Great British Railways, the state ticketing operator the government still plans to launch. Signal, and a sentiment overhang that stays until the case is resolved on the regulator’s timetable, not the company’s.
Ceres Power (LON:CWR), -13.73% to 407.00p, looks like a momentum stock handing back its gains rather than reacting to anything new. The fuel-cell developer has been one of the market’s wildest rides this year on hopes of powering data centres, and it has drawn a string of broker downgrades warning the price ran well ahead of the company’s ability to manufacture at scale. With no fresh news I could find to feed it, a stock like this deflates quickly. It looks like a momentum unwind more than anything company-specific, and a reminder of how these things behave in both directions.
Chemring (LON:CHG), -9.16% to 570.50p, was simply the mid-cap end of the same defence pullback that caught Babcock and BAE. Noise.
Raspberry Pi (LON:RPI), -9.08% to 606.00p, is another high-sentiment technology name that swings hard both ways, caught this week in a broader cooling on the racier corners of tech. I could not pin the move to any specific piece of news, which is usually the market simply repricing its appetite for risk rather than reacting to the company. Read it as noise.
Watches of Switzerland (LON:WOSG), -7.61% to 680.00p, had no single headline either, but the JD Sports warning put the squeezed consumer front of mind, and a luxury retailer is exactly the sort of name that gets sold when the market decides shoppers are tightening up. The reported take-private talks around the group sit underneath as a floor. Signal, on the read-through more than on the company.
Idea of the week: the mid-cap turnaround trade
Look past the metals and the two most interesting moves of the week were Oxford Nanopore and Kainos, up almost 40% and a third. Neither ran because it suddenly sold a great deal more than the market expected. Both ran because the profit story turned.
Nanopore’s revenue was soft and everyone knew it. What moved the shares was margin and cost discipline, the loss halving, and a new boss drawing a tighter map of where the company actually makes money. Kainos did not even wait for results, it told the market in advance that the year would beat forecasts. In both cases the market re-rated a business on the shape of its earnings rather than the size of them.
That is worth filing away, because it is the opposite of what has driven the index for two years. The FTSE 100’s gains have come from oil, banks and now metals, the big cash machines that respond to the macro. The mid-caps have been left behind, down at valuations that look cheap against both their own history and their overseas peers. When one of them proves its profits are turning, the re-rating can be violent, precisely because so little good news was priced in. Nanopore and Kainos are this week’s evidence that the mid-cap discount closes fastest for the names that give the market a reason.
On the watchlist
One name sits right on top of the week’s central question. Fresnillo (LON:FRES) led the FTSE 100 because silver did the heavy lifting, and its leverage to the metal is the whole point of owning it. That leverage is also the risk. The entire metals rally is leaning on one belief, that the Fed holds rates where they are or eases from here, and that belief gets its real test at the Federal Reserve’s meeting on 15 and 16 September. A stronger US inflation print before then, or a more hawkish tone at the meeting itself, and the same maths that tripled a silver miner’s profit on the way up runs in reverse. The barrel of Brent that is keeping UK gilt yields high is the thing that could deliver exactly that print. That is the tension to watch into September.
Thanks for reading,
Ollz
This article is for informational and educational purposes only and does not constitute financial advice. The author may hold positions in securities mentioned. Always do your own research and seek independent financial advice before making any investment decision. Capital is at risk.
Sources
[1] MINING.COM, https://www.mining.com/gold-silver-miners-surge-as-treasury-doubles-buybacks/
[2] Reuters (via Euronext), https://live.euronext.com/en/financial-news/jd-sports-cuts-profit-outlook-us-sales-drop-shares-tumble
[3] Competition and Markets Authority (GOV.UK), https://www.gov.uk/government/news/trainline-virgin-atlantic-and-red-driving-school-investigated-for-drip-pricing
[4] Bloomberg, https://www.bloomberg.com/news/articles/2026-08-19/oxford-nanopore-ceo-s-1-billion-sales-goal-sends-stock-soaring
[5] interactive investor, https://www.ii.co.uk/analysis-commentary/ii-view-shares-uk-tech-company-kainos-soar-ii540010
[6] MINING.COM, https://www.mining.com/fresnillo-profit-triples-on-gold-silver-prices-rally/
[7] Fidelity / Sharecast, https://www.fidelity.co.uk/shares/stock-market-news/market-reports/
[8] Euronext, https://live.euronext.com/en/financial-news/ftse-100-falls-jd-sports-tumbles-profit-warning