

Disclosure: Corfe Capital holds Henderson Far East Income (LON:HFEL) as a long-standing position in the portfolio. This article is for information and does not constitute financial advice or a recommendation to buy or sell. Do your own research and consider your own circumstances, or speak to a regulated adviser, before making any investment decision. Capital is at risk and past performance is no guide to future returns.
Dear reader,
A subscriber asked me for a deep dive on Henderson Far East Income (LON:HFEL), one of the longer-standing positions in the portfolio, and it’s a fair request because I’ve never given it the full write-up it deserves. It has simply sat there and done its job. This is a trust I’ve held for years, and it earns its place for a few plain reasons. It hands me a single line of exposure to the whole Asia Pacific region, spread across sixty-odd holdings and a dozen-plus markets. Much of that is ground a UK retail investor cannot easily cover alone, since a good chunk of Asian income sits in names that are awkward to hold directly from an ISA or SIPP. One purchase does the reaching for me. It pays a yield knocking on ten percent, comfortably one of the highest in the portfolio. And it pays it quarterly, in a steady rhythm, with a payout that has grown for eighteen years on the trot.
So on the face of it, this is the easy kind of review to write. Long-held position, does what it says, get paid every quarter. But something has changed since I last looked closely, and it is the sort of change that should make any honest holder stop and ask whether the thing they bought is still the thing they own. For most of the time I’ve held HFEL, the market wanted it at a discount. Today it sits on a premium, a touch above 262p against a net asset value near 249p, and the board has been issuing new stock into the demand. That is a genuine turn, and it reframes the whole question. So this is not a victory lap. It is a proper look at what I own, why I still own it, and whether the case that got me in still holds now the price has caught up.
If you want to see where HFEL sits alongside everything else I hold, weightings and all, the full portfolio is laid out in my latest monthly update:

What HFEL actually is
Start with the plumbing. HFEL is an investment trust, not a fund in the everyday sense. That means it is a company in its own right, listed on the London market, whose entire business is holding a portfolio of other companies’ shares. You buy shares in the trust, the trust buys shares in Asia. It is run by Sat Duhra at Janus Henderson, and it is incorporated in Jersey, with a second listing over in New Zealand.
The reason the structure matters is that a trust behaves differently from a normal open-ended fund, and those differences are the whole story with an income vehicle like this one. Because it is a fixed pool of capital that does not shrink when investors sell, the manager never has to dump holdings to meet redemptions, which suits illiquid, higher-yielding Asian names. It can borrow a little to invest more, known as gearing, currently running at around six percent. And crucially, it can hold money back in good years to top up the dividend in lean ones, smoothing the payout in a way an open-ended fund cannot. It is exactly how a trust racks up eighteen straight years of dividend growth, and later I will test how much is left in the tank.
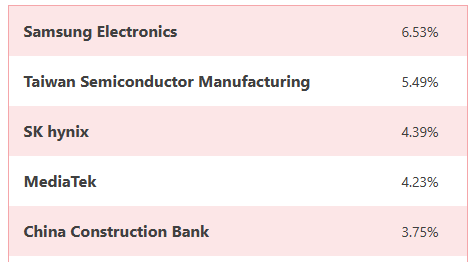
The mandate is high and rising income from the Asia Pacific region, with capital growth as the junior partner. There is no formal benchmark, though from this year the board measures itself against the MSCI AC Asia Pacific ex Japan Index. In practice Duhra runs a concentrated portfolio of sixty-odd names, with the top ten making up around a third of the whole thing. As at the end of July the largest position is Samsung Electronics at 6.5 percent, followed by Taiwan Semiconductor (TSMC) at 5.5 percent and SK Hynix at 4.4 percent, the trio that between them make most of the world's advanced memory and logic chips. Below that sits a run of Taiwanese tech names like MediaTek and United Microelectronics, a spine of big Chinese financials such as China Construction Bank and New China Life, and China's battery champion Contemporary Amperex, better known as CATL. It is a portfolio that has clearly leaned into the Asian tech and financials story, with those two sectors together accounting for well over half of it.
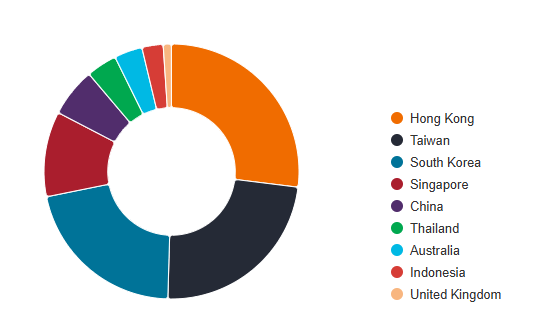
Geographically the trust is a North Asia story. As at the end of July the largest weighting is Hong Kong, followed by Taiwan and South Korea, with Singapore and mainland China behind them and only a thin tail in Thailand, Australia and Indonesia. One thing worth knowing for context: a lot of large Chinese companies list their shares in Hong Kong, so the Hong Kong slice captures a good chunk of what most people would think of as China exposure. Duhra has also been shifting the mix, leaning further into Korea over the past year on the back of the corporate reforms nudging Korean firms to treat shareholders better. So the trust a subscriber bought two years ago and the one they own today are not quite the same animal underneath. This is an actively run bet on where in Asia the income and growth sit, not a passive tracker you leave alone.
The performance question
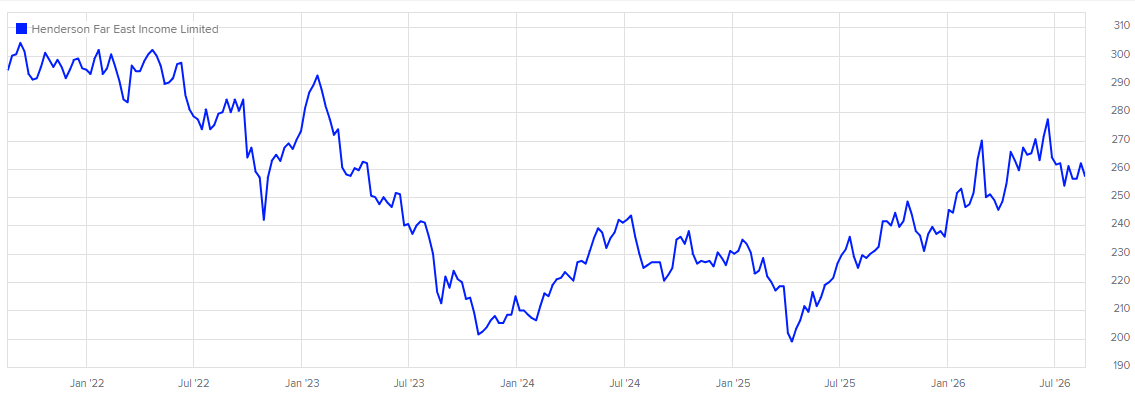
This chart is driven by two engines, not one. There is what the underlying Asian holdings are worth, the NAV, and there is the gap between that value and what the market will actually pay for it, the discount or premium. For most of the last five years both engines worked against the shares at the same time, which is why the falls were steeper than Asia alone would explain. Walk it through and the story writes itself.
In early 2022 the shares sat up around 300p. What followed was a grim year. Central banks began raising interest rates hard to fight inflation, and a trust bought mainly for its near double-digit yield is exactly the thing that falls out of fashion when cash and bonds suddenly pay you something. HFEL was also heavily weighted towards China and Hong Kong back then, and China spent 2022 locked down under zero-Covid while its property sector buckled. The low came in the autumn, around 245p, as China’s Party Congress cemented the leadership the market least wanted and global bond yields peaked. Both engines pulling down together.
Then a violent bounce, up towards 290p by January 2023, when China abruptly abandoned zero-Covid and everything Chinese rallied on the reopening. It did not last. Through 2023 the recovery fell apart, the property crisis deepened, and the shares slid all the way back to around 200p. This was the worst of it, and here the discount did real damage. As global interest rates climbed to levels not seen since before the financial crisis, income trusts across the board were marked down and their discounts blew out. Holders felt the Asian weakness and the widening discount at once. The choppy 2024 that followed was China stimulus hope flickering on and off, a big rescue package from Beijing in late September sparking a rally that faded as Trump won the US election and dragged tariff fears back into view.
Those fears produced the sharpest event on the chart. In early April 2025 Trump unveiled his “Liberation Day” tariffs, Asian markets were hit hardest of all, Hong Kong’s main index fell 13 percent in a single day, its worst since 1997, and HFEL bottomed near 198p. From there the shares have done little but climb, to a peak near 278p in the summer of 2026 before easing to today’s 260p or so. Trump paused the worst of the tariffs within days and by early 2026 the US Supreme Court had struck them down. The AI boom sent the Taiwanese and Korean chipmakers higher. And the discount did not just close, it flipped to a premium.
So the shares have had a barnstorming eighteen months. Which makes the next number the awkward one. Strip out the share-price drama and look at the NAV, the cleanest read on what the manager actually delivered, and even through this recovery HFEL has lagged the market it fishes in. In the six months to February the NAV total return was 23.3 percent against 26.2 percent from the MSCI AC Asia Pacific ex Japan index. And it barely matters which measure you pick, because the trust has quietly changed its comparator more than once and trailed all of them. In the year to August 2024 its NAV rose 11.9 percent against a high-yield Asian index up 17.4 percent. The year before that it fell 13 percent while the broad regional index dropped only 7. This year the board switched again, to the plain MSCI index, which it called more representative of the portfolio, and even then could only describe a near three point shortfall as having “broadly matched” the market. String these together and the real knock on HFEL emerges. Over most multi-year stretches, you would have made more in a plain Asian tracker.
The reason is baked into the mandate. To pay a near ten percent income, Duhra has to own things that pay him, and that pulls the portfolio towards value and dividends and away from the very biggest growth names that drive an index higher. He holds TSMC and SK Hynix, but less of them than the index does, precisely because their yields are thin. When those names lead the market, as they have all through the AI boom, HFEL is left a step behind. The income is not free. You fund it, in part, by giving up a slice of capital growth. So how you feel about the performance depends entirely on what you came for. If it was total return, HFEL has quietly cost you against a tracker for years, and even its best recent half did not close the gap. If it was a high, reliable, growing income, and you were relaxed about the capital keeping pace, it has done exactly what it says. Which brings us to the thing everyone actually holds it for.
The dividend, and whether it holds up
This is the reason anyone owns HFEL, so it deserves the closest look. The headline is genuinely impressive. The trust has raised its dividend for eighteen years in a row, through the financial crisis, Covid and everything since, and it pays quarterly, in November, February, May and August. The annual payout now runs to a shade over 25p a share, which at today’s price is a yield near 9.6 percent. Two more years of increases and it joins the small club the industry calls dividend heroes. On the face of it, this is the gold standard of income investing.
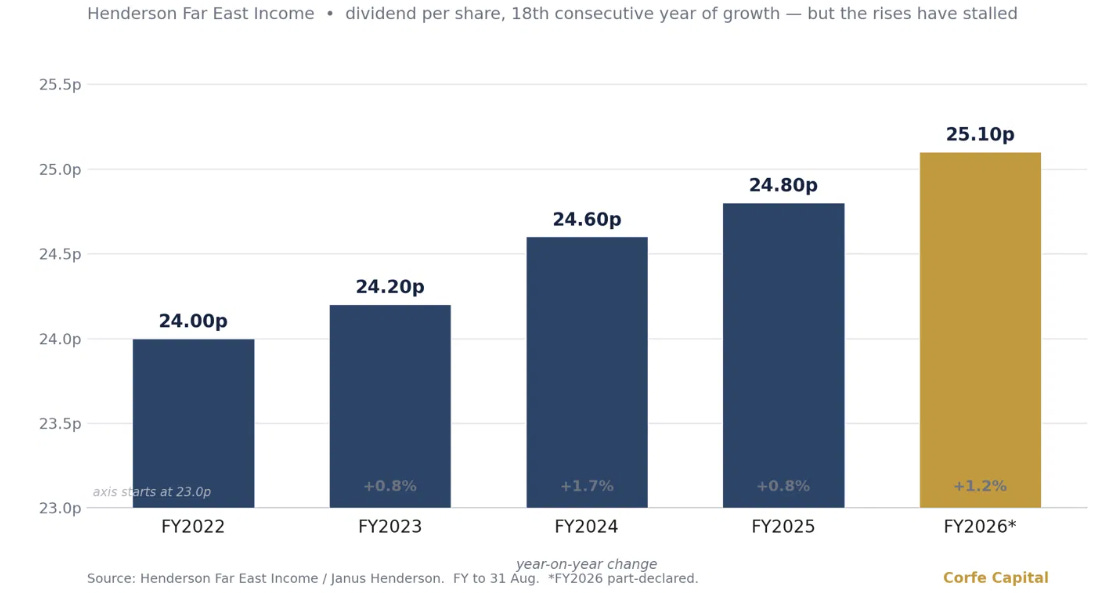
Look closer at the growth, though, and the shine comes off a little. Eighteen years of rises sounds like a dividend marching steadily upwards. The reality lately is a crawl. The most recent half-year increase was 0.8 percent, and across the last five years the dividend has grown at around one and a half percent a year. That is below inflation. So the streak is real, but it is being kept alive with token rises. You are being paid a very high income that is barely growing, rather than a rising income in any meaningful sense. For a trust whose entire pitch is a growing dividend, that is the single most important thing to understand about it right now.
Then the question every HFEL sceptic asks: is the dividend actually covered, or is the trust quietly paying you with your own money? Here the answer is more reassuring than the trust’s critics suggest, with one important caveat. On the company’s own accounts the dividend is covered by revenue, and behind that sits a revenue reserve, which is money held back in the good years that a trust can dip into to keep the dividend flowing in lean ones. That reserve is exactly why the eighteen-year streak survived years when Asian dividends fell. So this is not, on the face of it, a dividend being funded by selling down the portfolio.
The caveat is where that revenue comes from. A meaningful slice of it is not dividends dropping out of the holdings, but income manufactured by the options overlay. In plain terms, Duhra sells other investors the right to buy some of his shares at a set price later, and banks a fee for doing so. That fee counts as revenue and helps pay your dividend. It is a perfectly legitimate tool, and it is a big part of how you get to a near ten percent yield when the underlying Asian shares yield far less. But it is not free money. In exchange for those fees you cap some of your own upside, which is one more reason the capital growth lags. So the honest way to describe the dividend is this. It is covered, and it is backed by reserves, but the cover leans on manufactured income rather than pure dividends, and reasonable people can disagree about how high quality that makes it. It is safe enough. It is just not as pristine as eighteen unbroken years might lead you to believe.
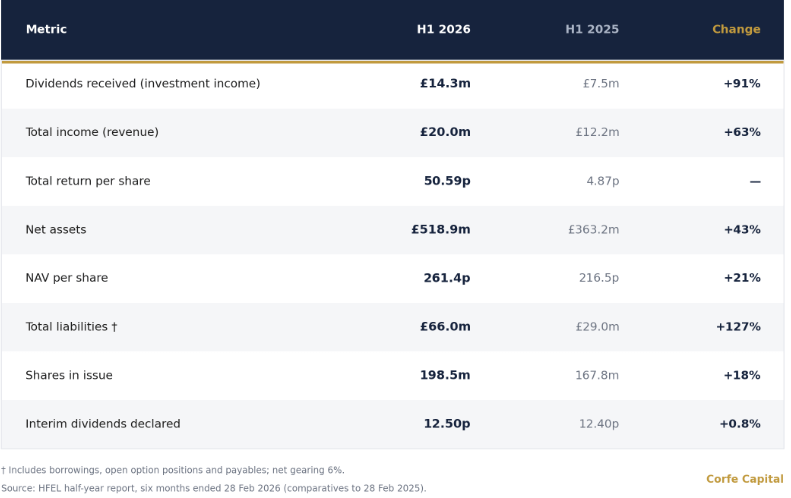
The financials underneath are in good order and, for once, moving the right way. The trust has grown to around £517m in assets, up from roughly £363m a year earlier, swelled both by the strong performance and by heavy demand for the shares, which has let it issue close to 21m new shares over the past year. That growth earned it promotion to the FTSE 250 in April. Costs are reasonable for an actively managed Asian trust, with ongoing charges of just under 1 percent, a flat management fee of 0.75 percent and no performance fee to worry about. Gearing, the borrowing the trust uses to invest a little more than its own money, sits at a modest 6 percent. None of this is a red flag. It is a bigger, cheaper-to-run, more liquid trust than it was two years ago.
From discount to premium, the thing that changed
