

Dear reader,
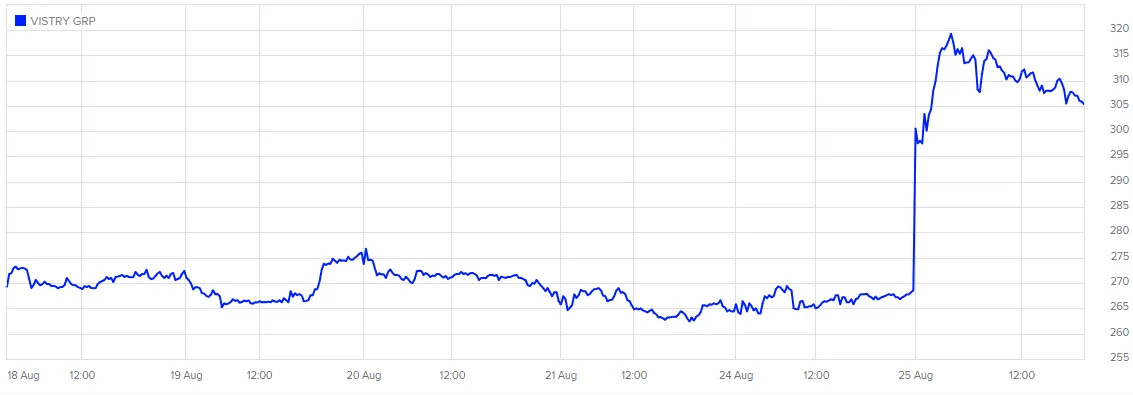
Vistry Group (LON:VTY) is one of the most shorted names on the London market. It is a company that rarely stays out of the headlines, and this morning it grabbed them again for opening sharply up 15% [2]. This came as the housebuilder confirmed it had been reappointed a strategic partner under the government’s new £39bn Social and Affordable Homes Programme and awarded £350m of direct grant funding, the largest award available to a single partner in this first phase [1].
The figure dwarfs what came before. The £350m is more than four times the £83m Vistry picked up at the equivalent stage of the last programme back in 2021, and comfortably exceeds the £278m it collected across the entire six years of that scheme [1]. This is non-repayable government money, earmarked to support more than 3,000 affordable homes, with management saying the first schemes will go into the ground before the year is out.
Set against a share price that began the day nearer its 52-week low of 220p than anywhere close to the 746p it traded at a year ago [2], the reaction is easy enough to understand. What the grant does not do is answer the questions that made Vistry the most shorted stock in the country in the first place. Those were still there on Monday, and a letter from Homes England does not make them disappear.
What the grant actually unlocks
To see why the market cared this much, it helps to remember how Vistry now makes its money. From 2022, Vistry shifted decisively away from relying primarily on private-market sales and rebuilt itself around what it calls partnerships. Under that approach it builds homes to order for housing associations, councils and other registered providers, the organisations that own and manage affordable housing, and increasingly folds those affordable homes in alongside open-market sales on the same site.
The appeal is that it strips a lot of the sales risk out of housebuilding. Rather than hoping buyers turn up once the roof is on, Vistry has a customer lined up before it breaks ground. The catch, and it has been a painful one this year, is that those customers can only buy when they have money of their own to spend. Housing associations spend grant funding handed to them by Homes England, and until this week nobody knew how the £39bn pot was going to be carved up.
By July, uncertainty over allocations had become a major brake on activity. In its trading update that month Vistry said demand from its partners was being held back precisely because the allocations had not been confirmed, and that it expected activity to recover once the decisions landed [6]. Tuesday’s announcement is that decision. Vistry’s own £350m is part of the picture, but the wider point is that £9.58bn has now been released across the sector, and the associations Vistry sells to finally know what they have to spend [1].
The grant was not the only thing in Tuesday’s statement. Vistry is also renegotiating framework agreements with ten of its largest partners, the standing arrangements that set out how much it will build for them and on what terms [6]. For a business whose entire pitch rests on visibility of future work, progress there may matter as much as the headline cheque.
How Vistry became the market’s favourite short
Vistry was not always the stock people bet against. As recently as 2024 it was being talked about as one of the smarter operators in the sector, on the back of a bold decision to tear up the way it did business.
From 2022 the company moved away from the traditional housebuilder’s model of putting up homes and selling them one at a time to private buyers. In its place it rebuilt itself around a mixed-tenure partnerships model: constructing homes to order for housing associations, councils and other registered providers, the organisations that own and manage affordable housing, and increasingly stacking those affordable homes alongside open-market sales on the same site. The logic was that it takes much of the sales risk out of building. Instead of hoping buyers appear once the roof is on, Vistry lines up a customer before it breaks ground. For a while the market loved it, and the shares were priced as though the company had found a way to keep growing through a downturn that was hurting everyone else.
Then two things went wrong. The first was self-inflicted. In late 2024 Vistry admitted it had understated build costs in its South division, forcing a run of profit downgrades and denting trust in management’s grip on its own numbers [5]. It did not help that the top job combined chairman and chief executive in one person, Greg Fitzgerald, a concentration of power that governance-minded investors had long been wary of. He has since stepped back, with Adam Daniels taking over as chief executive earlier this year [3].
The second problem was structural, and it matters more for what follows. That partnerships model has a catch: Vistry’s customers can only buy when they have money of their own to spend, and housing associations spend grant funding handed to them by the government. When that funding is uncertain, orders dry up. Through the first half of 2026 that is exactly what happened. Partner demand stalled, Vistry began discounting homes and slowing down sites to protect its cash [4], a fresh profit warning arrived in May, and the buyback, its programme of returning cash to shareholders by repurchasing its own shares, was suspended while Daniels launched a review of the business [3].
By the summer the picture was bleak on paper. The shares had roughly halved over twelve months, and close to a fifth of them had been sold short, meaning borrowed and sold by investors betting the price would fall further. No company on the London market was more heavily bet against [3]. That is the Vistry that walked into Tuesday’s announcement.
The grant, and what it actually changes
Which is what makes the timing of Tuesday’s news so pointed. One of the biggest issues weighing on Vistry was the drought in partner orders, and that drought existed because nobody knew how the government’s money would be divided. This announcement is the answer.
Vistry has been reconfirmed as a Strategic Partner to Homes England, the government agency that funds and oversees affordable housing, and awarded £350m of direct grant funding under the new £39bn Social and Affordable Homes Programme. Grant funding here means non-repayable government money, not a loan, earmarked to help deliver more than 3,000 affordable homes, with the first schemes due to start this year. It received the largest award Homes England could make to an individual strategic partner in this phase, and the scale is striking against Vistry’s own history: it is more than four times the £83m it was handed at the equivalent stage of the last programme in 2021, and it exceeds the £278m it collected across the whole of that six-year scheme [1].
It is worth putting the number in per-home terms. Spread across the 3,028 homes the award is expected to support, the £350m equates to roughly £116,000 per planned home, although that should not be confused with Vistry’s revenue or profit [6]. The grant supports the delivery economics of the schemes. The investment question is how much of the resulting construction activity ends up in Vistry’s sales, margins and cash flow.
Chief executive Adam Daniels framed it as continuity rather than rescue, noting that Vistry has taken direct grant funding under successive programmes for nearly twenty years. He welcomed a wider announcement expected to create more than 73,000 new homes, calling it “a much-needed stimulus” for Vistry, its partners and the sector as a whole [1].
The £350m matters, but the more important figure is arguably the one attached to the rest of the sector. Homes England released £9.58bn in this first tranche, spread across more than thirty strategic partners, most of them the housing associations and councils that Vistry actually sells to. For a company whose problem was that its customers had no confirmed budget, the useful part is not just its own cheque but the fact that its customers now have theirs. Vistry says it already has relationships with 29 of the 32 other partners named alongside it, and operates across all the regional mayoral authorities involved, which positions it to build not only against its own allocation but against theirs too [1].
There was a second, quieter line in the statement that may prove just as significant. Vistry is renegotiating framework agreements with ten of its largest partners, the standing contracts that set out how much it will build and on what terms [6]. Progress on those could improve visibility over future work, the central issue questioned by short sellers, although it will not necessarily guarantee attractive volumes or margins.
What none of this settles is the financial consequences. The grant funds delivery, it does not repair a balance sheet, restart the buyback or undo the cost problems that started the rot. It reopens the tap on demand. Whether that demand converts into the volumes and margins Vistry needs is the question the next set of results will have to answer.
Where this leaves Vistry, and the market it is building into
The read is that Tuesday changed the narrative without yet changing the accounts. The grant reopens the flow of orders that had dried up, and it does so for precisely the part of the business Vistry has staked its future on. But the balance sheet is still where it was on Monday. The buyback is still suspended, the cost problems in the South division are still fresh in the memory, and Daniels’ review of the business is still running. A confirmed pipeline of work is worth a great deal to a company that spent the summer being doubted, yet it only becomes worth something on paper once it converts into homes built at a decent margin. The first real test of that comes with the next set of results, not with the press release.
The backdrop it is building into is awkward. UK housebuilders have had a miserable year, the worst-performing corner of the FTSE 350, dragged down by mortgage rates stuck above 5% and a run of fiscal uncertainty that has kept buyers cautious [7]. The Bank of England held its base rate at 3.75% at the end of July, with inflation at 2.6% in June, above target and not obviously on a path lower [8]. Mortgage rates remained elevated, limiting the benefit investors had expected from lower borrowing costs. For a conventional housebuilder selling to mortgaged buyers, that is a headwind with no quick fix.
Here is where Vistry’s much-maligned pivot starts to look less like a liability. The affordable and partnerships model is largely insulated from mortgage rates, because the buyer is not a family stretching to afford a deposit, it is a housing association or council spending government money. When private demand is weak and borrowing is expensive, being the builder the state pays to keep building is not a bad place to stand. The very shift that left Vistry exposed to a funding drought this year is the one that could shelter it if the open market stays soft. Tuesday’s £9.58bn says the government intends to keep spending, and that it wants firms like Vistry doing the spending for it.
The next checkpoints are straightforward. Investors need to see how quickly the £350m is deployed, whether partner reservations recover, whether the ten framework agreements are renegotiated on acceptable terms, and whether additional volumes come through at margins that justify the capital tied up in construction. The crucial evidence will come from completions, cash generation, net debt and guidance, not from the size of the grant alone.
That does not make the shorts wrong, and it does not turn a beaten-down builder into a healthy one overnight. What it does is give Vistry something it has been short of all year: a reason to believe the order book is real, and a customer base with money to spend. Whether that is enough to change the numbers, rather than just the mood, is the question the rest of 2026 will settle.
Ollz.
References
Vistry Group PLC, “SAHP Funding Award” (RNS), Investegate. https://www.investegate.co.uk/announcement/rns/vistry-group--vty/sahp-funding-award/9738515
“Vistry Shares Jump After £350m Homes England Grant Award,” AskTraders. https://www.asktraders.com/analysis/vistry-shares-jump-after-350m-homes-england-grant-award/
“Housebuilders, consumer stocks and data firms: The most-shorted FTSE stocks,” Trustnet. https://www.trustnet.com/news/13481664/housebuilders-consumer-stocks-and-data-firms-the-most-shorted-ftse-stocks
“How did Vistry become the UK’s most shorted stock?,” City AM. https://www.cityam.com/how-did-vistry-become-the-uks-most-shorted-stock/
“Stockwatch: high stakes for one of UK’s most-shorted shares,” interactive investor. https://www.ii.co.uk/analysis-commentary/stockwatch-high-stakes-one-uks-most-shorted-shares-ii539411
“Vistry Shares Jump as £350 Million Government Funding Supports 3,028 Homes,” Yahoo Finance. https://uk.finance.yahoo.com/news/vistry-shares-jump-350-million-085524898.html
“UK Housebuilders Slide as Mortgage Rates Climb and Budget Uncertainty Drags on Demand,” AskTraders. https://www.asktraders.com/analysis/uk-housebuilders-mortgage-rates-budget-uncertainty-2026/
“UK Mortgage Rate Predictions 2026,” Apply Mortgages. https://www.applymortgages.co.uk/articles/uk-mortgage-rate-predictions/